How Much Can You Save by Making a Personal Loan Prepayment?
By bankcreds
4 Views
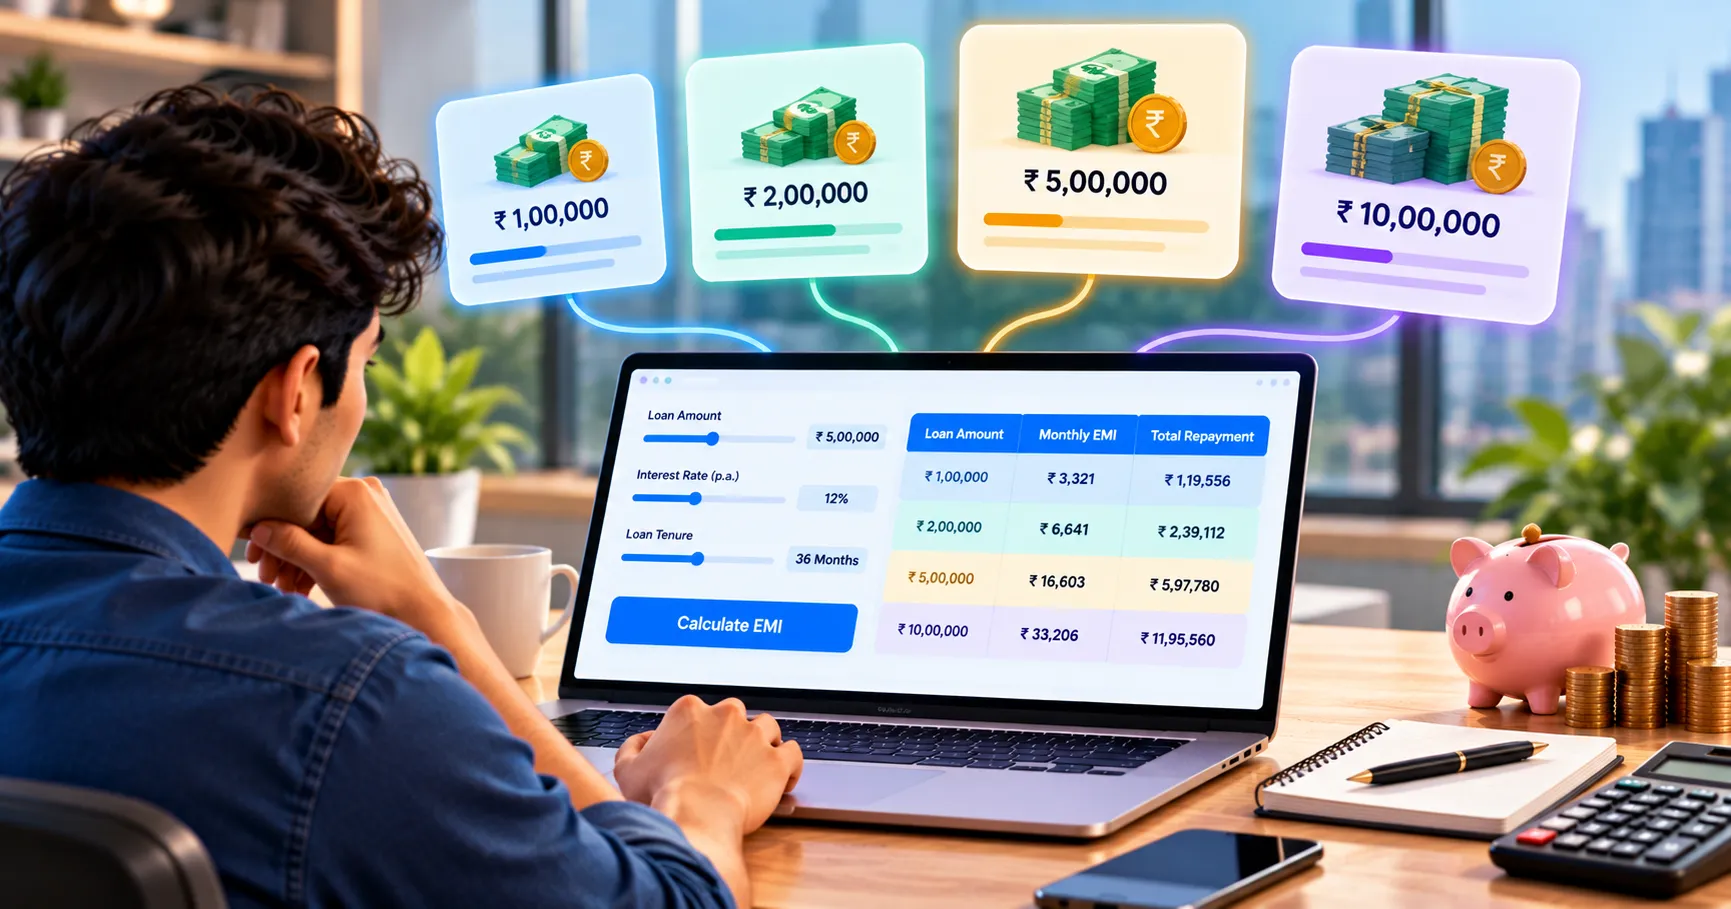
A personal loan prepayment can potentially reduce the interest you pay because an additional payment toward the outstanding principal can reduce the amount on which future interest is calculated. The actual savings depend on factors such as the prepayment amount, outstanding principal, remaining tenure, interest rate, and applicable charges. A loan prepayment calculator can help estimate the potential interest savings after making a part prepayment. Before prepaying, borrowers should compare the expected savings with any applicable prepayment or foreclosure charges.
What Is Personal Loan Prepayment?
Personal loan prepayment means paying some or all of your outstanding loan before the scheduled repayment date.
There are two common situations:
- Part prepayment
- Full prepayment or foreclosure
With part prepayment, you make an additional payment toward the outstanding principal while continuing the loan.
With full prepayment, you pay the amount required to close the outstanding loan according to the lender's terms.
The exact rules depend on the loan agreement.
How Does Personal Loan Prepayment Reduce Interest?
Interest on a loan is generally calculated based on the outstanding principal and applicable rate.
When you make an additional payment toward the principal, the outstanding amount can decrease.
For example, suppose your outstanding principal is ₹3 lakh. If you make a ₹50,000 additional principal payment, the outstanding amount may reduce to approximately ₹2.5 lakh, subject to the lender's accounting and applicable terms.
Future interest can then be calculated on the lower outstanding balance.
This is the basic reason prepayment may generate savings.
What Is a Loan Prepayment Calculator?
A loan prepayment calculator helps estimate how an additional payment may affect your repayment schedule.
Depending on the calculator, you may enter:
- Outstanding principal
- Current interest rate
- Remaining tenure
- Prepayment amount
- Current EMI
The calculator may then estimate:
- Revised outstanding balance
- Potential interest savings
- Revised tenure
- Revised EMI
The actual result depends on how the lender applies the prepayment.
How Much Can I Save by Prepaying a Personal Loan?
If you are asking how much can I save by prepaying a personal loan, the answer depends heavily on when you make the payment.
Prepaying earlier can potentially provide greater interest savings because there are more future instalments over which interest would otherwise be charged.
For example, suppose you have a loan with a significant outstanding balance and several years remaining. A substantial early prepayment can reduce the principal on which future interest would otherwise accrue.
However, if the loan is already close to completion, the potential savings may be smaller.
Personal Loan Prepayment Calculation
A personal loan prepayment calculation should consider both the outstanding balance and remaining tenure.
Suppose:
- Outstanding principal: ₹3,00,000
- Remaining tenure: 36 months
- Interest rate: 12%
- Current EMI: approximately ₹9,965
- Proposed prepayment: ₹75,000
The prepayment would potentially reduce the outstanding principal to approximately ₹2,25,000, before considering how the lender applies the payment.
The actual interest savings depend on whether the lender reduces the EMI, reduces the tenure, or applies another repayment adjustment.
Calculate Interest Savings After Prepayment
To calculate interest savings after prepayment, compare two scenarios:
Without Prepayment
Calculate the remaining interest based on the existing outstanding balance, interest rate, and remaining tenure.
With Prepayment
Reduce the outstanding principal by the planned prepayment amount and calculate the revised repayment cost.
The difference between the two scenarios provides an estimate of potential interest savings.
A calculator can make this comparison much faster.
Why Timing Matters
The timing of prepayment can influence the potential savings.
If you make a substantial prepayment earlier in the repayment schedule, the reduced principal can affect many future interest calculations.
If you make the same payment near the end of the loan, fewer instalments remain, so the potential interest reduction may be smaller.
Therefore, borrowers should evaluate the timing instead of assuming every prepayment produces the same savings.
Part Prepayment vs Full Foreclosure
A part prepayment allows you to reduce the outstanding principal without necessarily closing the loan.
Full foreclosure involves paying the amount required to close the loan completely.
Part prepayment may be useful when:
- You receive a bonus
- You have surplus savings
- You want to reduce future interest
- You want to shorten the tenure
Full foreclosure may be considered when you have sufficient funds to clear the remaining balance and the overall cost of closure is reasonable.
Should You Reduce EMI or Tenure After Prepayment?
After a prepayment, some lenders may provide options regarding how the revised repayment is structured.
You may potentially:
- Reduce EMI while maintaining a similar tenure
- Reduce tenure while maintaining a similar EMI
Reducing tenure can potentially generate greater interest savings because the loan is repaid sooner.
However, the appropriate option depends on your financial situation and lender's terms.
Check Prepayment Charges
Before making a personal loan prepayment, check the applicable loan agreement.
Potential costs can include:
- Prepayment charges
- Processing or administrative charges
- Taxes where applicable
- Other lender-specific fees
The expected savings should be compared with these costs.
For example, if estimated interest savings are ₹20,000 but applicable charges are ₹10,000, the net benefit would be considerably lower than the gross savings.
Should You Use Savings to Prepay?
Using savings for prepayment requires careful consideration.
Do not automatically use your entire emergency reserve to reduce a loan.
Consider whether you have sufficient funds for:
- Emergency expenses
- Insurance
- Essential household costs
- Other upcoming financial commitments
A financially sensible prepayment should not leave you without adequate liquidity.
Benefits of Personal Loan Prepayment
Potential benefits include:
- Lower outstanding principal
- Potential interest savings
- Shorter repayment period
- Reduced debt burden
- Potentially improved monthly cash flow after restructuring
However, the exact benefit depends on the loan's terms and the timing and amount of prepayment.
Final Thoughts
A personal loan prepayment can reduce the outstanding principal and potentially lower future interest costs. Using a loan prepayment calculator can help you estimate the impact of a part prepayment, compare different payment amounts, and calculate potential interest savings.
If you want to know how much can I save by prepaying a personal loan, compare the remaining repayment cost with and without the additional payment. Also consider the outstanding loan, applicable prepayment charges, your remaining tenure, and your available savings.
Prepayment can be useful, but it should be evaluated as part of your overall financial plan rather than treated as an automatic way to save money.
Related Reading
Why Business & Finance is Transforming the Global Industry Landscape
Welcome to our in-depth exploration of Business & Finance. In an era defined...
Expert Insights: Navigating the Complex World of Business & Finance
Welcome to our in-depth exploration of Business & Finance. In an era defined...